Jumbo Loans Phoenix & Scottsdale AZ | 2026 Homebuyer Guide
Jumbo Loans in Phoenix & Scottsdale, AZ: 2026 Homebuyer Guide
Buying a higher-priced home in Phoenix or Scottsdale? Jumbo financing may allow qualified buyers to purchase with as little as 10% down, qualify using alternative income documentation, or access specialized financing based on their profession and financial profile.
If you're buying a home in Scottsdale, Phoenix, Paradise Valley or elsewhere in Maricopa County, don't automatically assume you need 20% down—or that being self-employed means your tax returns are your only path to qualifying.
Jumbo financing options may be available for:
W-2 employees
Self-employed borrowers
Business owners and entrepreneurs
Doctors and eligible medical professionals
Borrowers with substantial assets
Buyers who need alternative income documentation
The right jumbo financing strategy depends on your credit, income, down payment, debt-to-income ratio, available reserves, loan amount and property type.
What Is a Jumbo Loan?
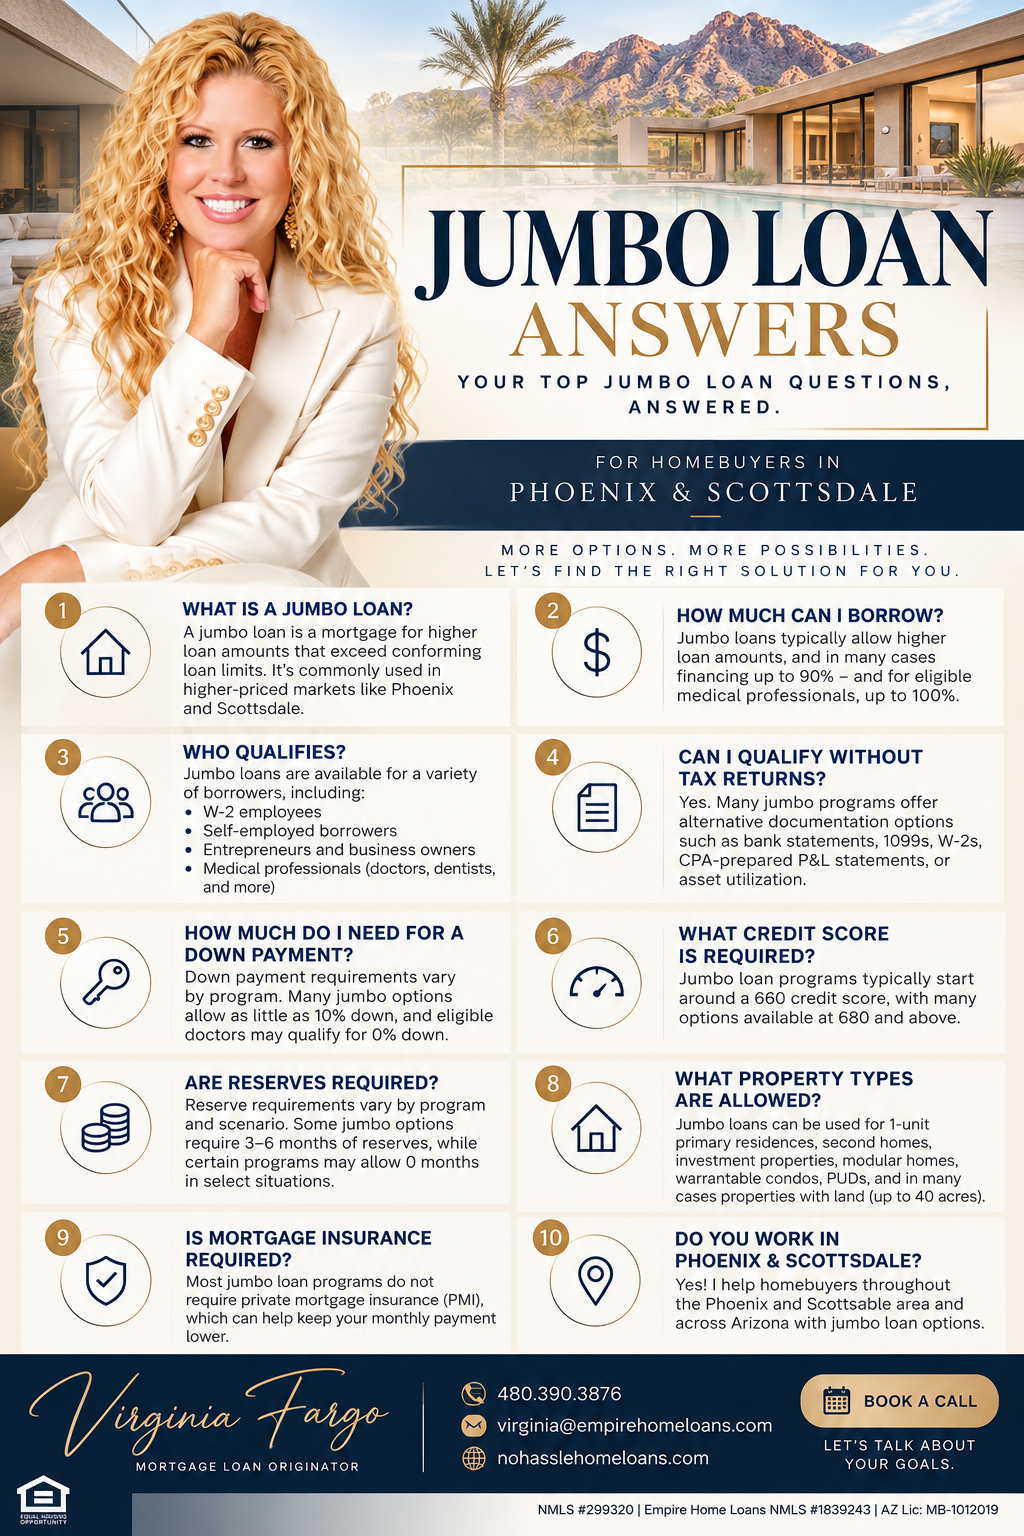
A jumbo loan is a mortgage used when the desired loan amount exceeds the applicable conforming loan limit.
Jumbo loans are commonly associated with luxury real estate, but “jumbo” describes the mortgage amount, not whether the property is officially considered a luxury home.
For buyers shopping higher-priced homes in Scottsdale, Phoenix and Paradise Valley, jumbo financing may become an important part of the homebuying conversation.
Why Does Jumbo Financing Matter in Scottsdale & Phoenix?
Higher-priced real estate throughout the Phoenix–Scottsdale market can require buyers to consider financing beyond traditional conforming mortgages.
That doesn't necessarily mean making a 20% down payment.
Depending on the borrower's qualifications, jumbo financing may provide:
Up to 90% financing for certain borrowers
Alternative income documentation for eligible self-employed buyers
Bank-statement qualification
Asset-utilization options
Specialized financing for eligible medical professionals
Up to 100% financing for certain qualifying medical professionals
Options without traditional tax-return documentation
Your income structure can be just as important as your income amount when determining which option fits.
How Much Do I Need to Put Down on a Jumbo Loan in Arizona?
Qualified Phoenix and Scottsdale jumbo borrowers may be able to purchase with as little as 10% down. Certain eligible medical professionals may qualify for 0% down.
Some jumbo financing options provide up to 90% loan-to-value (LTV), meaning a qualified buyer may be able to finance 90% of the purchase price.
The specific down-payment requirement depends on factors including:
Credit score
Loan amount
Income documentation
Debt-to-income ratio
Available reserves
Occupancy
Property type
The jumbo guidelines reviewed for this guide include options providing up to 90% LTV, although DTI and reserve requirements can become more restrictive as LTV increases.
Can I Buy a Scottsdale Home With 10% Down?
Potentially, yes. Some jumbo financing options allow qualified borrowers to purchase with 10% down.
For example, a buyer considering a $1.5 million Scottsdale home might assume a 20% down payment is required.
Twenty percent would equal $300,000.
A qualifying 10% down structure would equal $150,000.
That's a $150,000 difference in the amount of money committed to the down payment.
This doesn't mean 10% down is appropriate or available for every borrower. Credit, income, DTI, reserves and the complete financial profile must meet the applicable underwriting requirements.
But before automatically liquidating investments or moving hundreds of thousands of dollars into a down payment, it can be worth comparing available jumbo structures.
Can I Get a Jumbo Loan Without Tax Returns?
Yes. Certain jumbo programs allow qualified borrowers to document income without relying on traditional personal tax returns.
This can be particularly valuable for self-employed borrowers, entrepreneurs and business owners whose taxable income doesn't necessarily reflect their actual cash flow.
Depending on the borrower's situation, alternative documentation may include:
12-month personal bank statements
12-month business bank statements
W-2 or 1099 documentation
CPA-prepared profit-and-loss statements
Asset-utilization methods
The alternative-documentation guidelines reviewed for this page provide up to 90% LTV for certain bank-statement and other documentation scenarios, while the supplied CPA-prepared P&L and asset-utilization options have lower maximum LTVs.
Can Self-Employed Buyers Get a Jumbo Mortgage in Scottsdale?
Yes. Being self-employed doesn't automatically prevent you from qualifying for a jumbo mortgage in Scottsdale or Phoenix.
The important question is how your qualifying income will be documented.
A successful business owner may generate substantial cash flow while reporting lower taxable income after legitimate business deductions.
Instead of assuming your tax returns are the only way to qualify, we can evaluate whether an allowable alternative such as bank statements, 1099 income, a CPA-prepared P&L or eligible assets provides another way to document your ability to repay the mortgage.
Scottsdale Jumbo Example: Self-Employed Business Owner
Imagine you're purchasing a $1.5 million home in Scottsdale.
You own a successful business and have strong monthly cash flow, but your tax returns show considerably less income because of business deductions.
You may assume:
“My tax returns don't show enough income, so I can't qualify for the house.”
That isn't necessarily the end of the conversation.
Possible solution:
A jumbo mortgage using bank statements or another eligible alternative income-documentation method may be worth evaluating rather than relying exclusively on traditional tax returns.
The objective is to find the documentation method that accurately fits your financial situation while meeting applicable underwriting requirements.
What Credit Score Do I Need for a Jumbo Loan?
Some jumbo financing options may begin around a 660 FICO, while traditional full-documentation jumbo programs may begin around 680 or higher, depending on the program.
The alternative-documentation guidelines supplied for this guide show a minimum FICO of 660 for one financing pathway.
The traditional full-documentation jumbo guidelines reviewed show minimum credit scores around 680+, depending on the specific program.
Meeting a minimum credit score doesn't guarantee approval.
Your overall credit history, income, debts, assets, reserves, loan amount and property are also evaluated.
How Much Can I Borrow With a Jumbo Loan?
There isn't one maximum jumbo loan amount that applies to every borrower.
Your potential loan amount depends on your complete financial profile and the specific financing program.
Important factors include:
Income + monthly debts + credit + down payment + available assets + reserves + property type.
This is why two buyers purchasing similarly priced Scottsdale homes may qualify for very different financing structures.
Rather than starting with, “What's the biggest jumbo loan available?”, a better question is:
“What financing structure fits my income, assets and homebuying goals?”
Do Jumbo Loans Require Cash Reserves?
Many jumbo loans require cash reserves, but the amount varies by program and borrower profile.
Reserves are assets remaining after closing that demonstrate your ability to continue making your housing payment.
The alternative-documentation guidelines reviewed for this page generally call for approximately 3–6 months of reserves, depending on the documentation method.
Traditional jumbo reserve requirements vary by program, with some options in the supplied material beginning around three months.
Don't assume you need a particular dollar amount in reserves until your complete scenario has been reviewed.
Does My Debt-to-Income Ratio Matter With a Jumbo Loan?
Yes. Debt-to-income ratio can become especially important when you're making a smaller down payment on a jumbo loan.
Some jumbo programs become more restrictive as LTV increases.
The guidelines reviewed for this guide specifically note that DTI can tighten significantly at higher LTVs.
This means a buyer with 10% down and a higher DTI may have fewer financing choices than someone purchasing the same home with a larger down payment or lower monthly debt obligations.
That's why I recommend reviewing down payment and DTI together, rather than looking at either number by itself.
Can Doctors Buy a Phoenix or Scottsdale Home With 0% Down?
Certain eligible doctors and medical professionals may qualify for up to 100% financing with no monthly private mortgage insurance (PMI).
The medical-professional financing reviewed for this guide provides:
Up to 100% LTV
Loan amounts up to $2 million
Minimum 680 FICO
No mortgage insurance
Eligible medical professionals can include certain MDs, DOs, DDS/DMDs, PharmDs, DVM/VMDs, DPMs and qualifying CRNAs with DNP/DNAP credentials.
This can be especially useful for an eligible physician who has strong earning potential but doesn't want to liquidate a significant amount of savings for a large down payment.
Scottsdale Jumbo Example: Physician Relocating to Arizona
Imagine you're a physician relocating to Scottsdale or Phoenix for a new medical position.
You have:
Strong future income
Good credit
An executed employment offer
Medical-school debt
Savings you would prefer to preserve
You may not necessarily need to wait until you've accumulated months of paychecks or saved a traditional 20% down payment.
Possible solution:
Eligible medical professionals may qualify for specialized financing offering up to 100% financing with no PMI, subject to applicable guidelines and underwriting approval.
Can a Doctor Qualify Before Starting a New Job in Arizona?
Potentially, yes. An eligible medical professional may be able to qualify using an executed employment offer letter before starting the new position.
The guidelines reviewed for this guide allow an executed employment offer letter, with the employment start date generally within 150 days of the Note date.
Qualifying deferred student loans may also be excluded from DTI, while eligible gift funds and retirement assets may help satisfy reserve requirements.
This can be particularly valuable for medical professionals relocating to the Phoenix–Scottsdale area for a new position.
Phoenix Jumbo Example: High-Income W-2 Buyer
Imagine you're a high-income W-2 employee purchasing a higher-priced home in Phoenix.
You have:
Stable W-2 income
Strong credit
Documented assets
Money available for a down payment
You don't necessarily need an alternative-documentation mortgage simply because the loan amount is jumbo.
Possible solution:
Traditional full-documentation jumbo financing may provide up to 90% LTV for qualified borrowers, depending on the program and complete financial profile.
The goal is to compare available options rather than putting every jumbo borrower into the same financing structure.
Do Jumbo Loans Require Mortgage Insurance?
Mortgage-insurance requirements vary depending on the jumbo program.
Don't assume the mortgage-insurance rules are identical to those of conventional conforming loans.
For example, the medical-professional financing reviewed for this guide specifically provides no mortgage insurance, including eligible financing up to 100% LTV.
For other jumbo borrowers, mortgage-insurance requirements should be evaluated based on the specific financing structure.
What Types of Properties Can Be Financed With a Jumbo Loan?
Property eligibility varies by jumbo program.
Depending on the financing option, eligible properties may include:
One-unit primary residences
Second homes
Investment properties
Single-family residences
Warrantable condominiums
Planned Unit Developments (PUDs)
Modular homes
Certain properties with acreage
The medical-professional guidelines reviewed for this guide specifically include 1-unit properties, modular homes, warrantable condos, PUDs and eligible properties with up to 40 acres.
If you're considering an unusual property, condo or home with substantial acreage, I recommend reviewing the property eligibility early.
Can I Use a Jumbo Loan to Buy a Scottsdale Condo?
Potentially, yes. Jumbo financing may be available for eligible Scottsdale and Phoenix condominiums.
However, qualifying the borrower is only part of the equation.
The condominium itself may also need to satisfy applicable program requirements.
If you're considering a higher-priced condo in Scottsdale, I recommend reviewing the condo project before getting too far into the transaction.
Is a Jumbo Loan Only for Luxury Real Estate?
No. “Jumbo” refers to the mortgage amount—not whether a property is officially considered a luxury home.
However, jumbo financing frequently comes into play when purchasing higher-priced real estate in communities such as Scottsdale, Paradise Valley and parts of Phoenix.
The home can be beautiful, modest, contemporary, historic or luxurious. The financing classification is determined by the loan amount and applicable loan limits—not the home's style.
Should I Put 20% Down on a Scottsdale Luxury Home?
Not automatically.
Having enough money to put 20% down doesn't necessarily mean that's the only structure you should consider.
For example, a qualified buyer may want to compare:
20% down versus 15% down versus 10% down
The comparison should consider:
Interest rate
APR
Monthly payment
Closing costs
Reserve requirements
Cash remaining after closing
Long-term financial goals
For some buyers, a larger down payment makes sense.
For others, preserving additional liquidity may be important.
The objective isn't simply to make the smallest down payment possible. It's to determine which financing structure best fits your overall financial situation.
I'm Buying a Higher-Priced Home in Scottsdale. When Should I Get Pre-Approved?
Before you begin seriously touring homes or writing offers.
Jumbo underwriting can involve more variables than a standard mortgage.
An early jumbo pre-approval can help determine:
Your potential purchase price
How much you may need for a down payment
Which income-documentation method fits your situation
Whether tax returns are necessary
Your potential reserve requirement
How your existing monthly debts affect qualification
Whether the property type creates additional requirements
This is particularly important for self-employed buyers.
I'd rather identify the correct income-documentation strategy before you fall in love with a Scottsdale property than discover a financing problem after you're already under contract.
Which Jumbo Loan Strategy Fits You?
The first question shouldn't be:
“Which jumbo loan product should I use?”
It should be:
“What does my financial situation require?”
If you're a traditional W-2 borrower:
Full-documentation jumbo financing may be the logical place to start.
If you're self-employed:
We may need to compare traditional income documentation with bank statements, 1099 income, a CPA-prepared P&L, eligible assets or other available documentation methods.
If you're an eligible medical professional:
We can determine whether specialized physician financing provides an advantage, including the possibility of higher LTV financing and no PMI.
If you're trying to preserve cash:
We can compare different down-payment structures rather than automatically assuming 20% down is required.
The right jumbo mortgage should be built around the borrower—not the other way around.
Jumbo Financing Throughout Phoenix, Scottsdale & Maricopa County
I help homebuyers explore jumbo financing throughout the Phoenix–Scottsdale metro area and Maricopa County, including:
Scottsdale • Phoenix • Paradise Valley • Tempe • Chandler • Gilbert • Mesa and surrounding Arizona communities
Whether you're a W-2 executive, entrepreneur, business owner, self-employed professional or medical professional, the first step is understanding which financing options actually fit your situation.
Buying a Higher-Priced Home in Phoenix or Scottsdale?
Don't assume you need 20% down, perfect credit or traditional tax returns before exploring your options.
If you're considering a higher-priced home in Scottsdale, Phoenix, Paradise Valley or elsewhere in Maricopa County, let's review the numbers before you decide how much money to put down.
We can look at your:
Desired purchase price
Estimated credit profile
Employment and income structure
Existing monthly debts
Available down payment
Assets and reserves
Property type
Homebuying goals
Then we can determine which available jumbo financing structures fit your individual situation.
Loan programs and guidelines are subject to change without notice. Not all borrowers or properties will qualify. Loan amounts, LTV, DTI, credit requirements, reserves, income documentation, mortgage insurance and property eligibility are subject to applicable program requirements and underwriting approval. Verify current guidelines before making financing decisions.
About Virginia Fargo
Virginia Fargo, providing No Hassle Home Loans, the trusted mortgage consultant, home loan advisor in Scottsdale & across Maricopa County, the leading mortgage broker dedicated to helping consumers save money specializing in home loans, first-time homebuyers, relocation, affordability and self-employed borrower financing.