Physician Home Loans Phoenix & Scottsdale AZ | 0% Down Options
Physician Home Loans in Phoenix & Scottsdale, AZ: 0% Down Options With No PMI
Yes. Eligible doctors and medical professionals buying a home in Phoenix or Scottsdale, Arizona may qualify for a physician mortgage with up to 100% financing, no monthly private mortgage insurance (PMI), and loan amounts up to $2 million.
Physician home loans are designed around financial situations that are common among medical professionals: high student loan balances, limited savings after medical school or residency, relocation for a new position, or having a signed employment contract but not yet receiving a paycheck.
If you're a doctor or medical professional buying a home in Phoenix, Scottsdale, Paradise Valley or elsewhere in Maricopa County, a physician mortgage may give you another option besides making a large conventional down payment.
What Is a Physician Mortgage Loan?
A physician mortgage, sometimes called a doctor loan or medical professional mortgage, is a home loan designed specifically for qualifying medical professionals.
Eligible borrowers may receive benefits that aren't typically available with traditional mortgage financing, including:
Up to 100% financing
Loan amounts up to $2 million
No monthly PMI
Minimum 680 FICO
Ability to qualify with an eligible future employment offer letter
Certain deferred student loans may be excluded from DTI
Gift funds and eligible retirement assets may help satisfy reserve requirements
All financing is subject to complete underwriting approval and applicable program requirements.
Can Doctors Buy a Home With 0% Down in Phoenix or Scottsdale?
Yes, eligible medical professionals may qualify for up to 100% financing on a primary residence in Phoenix, Scottsdale and surrounding Arizona communities.
This can be especially valuable for doctors who have substantial income or future earning potential but don't want to drain their savings to make a large down payment.
Remember that 0% down doesn't necessarily mean $0 due at closing. Closing costs, prepaid taxes, homeowners insurance and other expenses may still be required unless they're covered through an allowable credit or other eligible source.
What Would 100% Physician Financing Look Like on a $1 Million Scottsdale Home?
Here's a simple hypothetical example:
Scottsdale purchase price: $1,000,000
Down payment: $0
Potential loan amount: $1,000,000
Loan-to-value: 100%
Monthly PMI: $0
The borrower would still need to qualify based on credit, income, employment, assets, debt-to-income ratio and all applicable underwriting requirements.
Closing costs and prepaid expenses may also be required.
This is one reason physicians shouldn't automatically assume they need $100,000 or $200,000 saved for a down payment before looking at Scottsdale homes.
Who Is Eligible for a Physician Home Loan?
At least one borrower must hold an eligible medical degree.
Eligible medical professionals can include:
MD — Doctor of Medicine
DO — Doctor of Osteopathic Medicine
DDS — Doctor of Dental Surgery
DMD — Doctor of Dental Medicine
PharmD — Doctor of Pharmacy
VMD or DVM — Doctor of Veterinary Medicine
DPM — Doctor of Podiatric Medicine
Certain CRNAs with a DNP or DNAP
Eligibility doesn't automatically mean loan approval. Your complete financial and employment profile must still satisfy underwriting requirements.
I'm Relocating to Work at Mayo Clinic in Phoenix. Can I Buy Before I Start My Job?
Potentially, yes.
An eligible physician may be able to qualify using a fully executed employment offer letter before beginning the new position.
For eligible W-2 medical professionals, the employment start date may be as far as 150 days after the Note date, subject to program requirements.
For eligible 1099 or contract medical professionals, the permitted timeframe is generally shorter, with employment beginning within 60 days of the Note date.
This can be particularly useful for doctors relocating to the Valley for employment with organizations such as Mayo Clinic, HonorHealth, Banner Health or other Phoenix-area medical providers.
Instead of waiting until you've started your new job and accumulated pay stubs, you may be able to explore homeownership before your employment begins.
Can Medical School Student Loans Be Excluded From My DTI?
Qualifying deferred student loans may be excluded from the debt-to-income ratio under this physician mortgage program.
That's a significant distinction for some medical professionals.
A doctor may have strong income and excellent long-term earning potential while simultaneously carrying a substantial medical-school loan balance.
Under many mortgage programs, student loan obligations can affect the borrower's debt-to-income ratio and purchasing power.
This physician mortgage provides different treatment for certain deferred student loans, subject to program requirements.
What Credit Score Do I Need for a Physician Mortgage in Arizona?
The minimum credit score for this physician mortgage program is 680 FICO.
The program also generally requires at least a 24-month credit history with a qualifying tradeline.
A 680 score doesn't guarantee approval. Credit history, income, employment, assets, debts, loan amount and property eligibility are all considered during underwriting.
Can a Physician Mortgage Really Have No PMI With 0% Down?
Yes. Eligible borrowers can receive up to 100% financing without monthly private mortgage insurance.
That's one of the primary differences between this physician mortgage and many low-down-payment conventional mortgage options.
Private mortgage insurance can add another expense to a monthly housing payment when a conventional borrower puts less than 20% down.
With this physician mortgage, eligible borrowers don't have that monthly PMI expense—even with qualifying 100% financing.
How Much Can a Physician Borrow?
This physician mortgage provides financing up to $2 million, subject to loan-to-value limits and underwriting requirements.
Maximum debt-to-income ratios depend upon the financing structure.
For financing between 90.01% and 95% LTV, the maximum DTI may be as high as 50%.
For financing above 95% LTV, maximum DTI is generally 45%.
Certain ARM and 15-year fixed-rate transactions also have a 45% maximum DTI.
Rather than trying to calculate your qualification from a DTI percentage alone, I recommend having your complete financial profile reviewed.
Do I Need Cash Reserves?
It depends on the loan amount and LTV.
For financing at 95% LTV or below, loans up to $1.5 million may require no reserves, while loans above $1.5 million through $2 million may require 3 months of reserves.
For financing above 95% LTV, loans up to $1.5 million generally require 3 months of reserves, while loans above $1.5 million through $2 million generally require 6 months of reserves.
Gift funds and 100% of eligible retirement accounts may be considered toward reserve requirements, subject to program guidelines.
What Types of Homes Can Doctors Purchase?
Eligible properties can include:
One-unit single-family residences
Warrantable condominiums
Planned Unit Developments (PUDs)
Modular homes
Eligible properties with up to 40 acres
The property must satisfy applicable program and underwriting requirements.
Can I Use a Physician Loan to Buy a Scottsdale Condo?
Potentially, yes. Warrantable condominiums are eligible under this physician mortgage program.
The individual borrower must qualify, and the condominium itself must meet applicable eligibility requirements.
If you're considering a Scottsdale or Phoenix condo, I recommend reviewing the condominium project early in the process rather than waiting until you're deep into escrow.
Are Physician Loans Only for First-Time Homebuyers?
No. You don't have to be a first-time homebuyer to use a physician mortgage.
Both newer and established eligible medical professionals may qualify.
The better question is whether a physician mortgage provides an advantage for your particular financial situation compared with conventional or other available financing.
Is a Physician Mortgage Better Than a Conventional Loan?
Neither option is automatically better.
A physician mortgage may be particularly attractive when you want to preserve cash, have qualifying deferred student loans, are beginning a new medical position, or want to avoid monthly PMI with a small or zero down payment.
Conventional financing may be more attractive in other situations.
I believe physicians should compare both options rather than assuming that a physician mortgage is automatically the best loan simply because they're a doctor.
The right comparison should consider the interest rate, APR, down payment, closing costs, monthly payment, mortgage insurance, cash remaining after closing and long-term financial objectives.
I'm Moving to Arizona for a New Medical Position. When Should I Get Pre-Approved?
Before you begin seriously touring homes.
This is especially important if you're relocating to Scottsdale or Phoenix and will be using a future employment contract to qualify.
Getting your financing reviewed early can help establish:
Whether your medical degree is eligible
Whether your employment offer meets program requirements
How your student loans will be treated
Your potential maximum purchase price
How much cash you may need at closing
Whether 100%, 95% or another financing structure makes sense
Which properties fit the loan requirements
It also gives your Arizona real estate agent a clearer price range when beginning the home search.
Physician Mortgage Example: Relocating to Scottsdale
Imagine a physician relocating to Scottsdale for a new position.
The physician has:
An executed employment contract
Excellent future income
Deferred medical-school loans
Good credit
Money saved, but doesn't want to drain savings for a large down payment
Instead of automatically putting 10% or 20% down, we can evaluate whether physician financing could allow the borrower to:
Use the new employment contract → potentially exclude eligible deferred student loans from DTI → finance up to 100% → avoid monthly PMI → preserve more cash after closing.
That preserved cash could be important when relocating, furnishing a home, establishing an emergency fund or simply maintaining liquidity.
What Areas Do You Serve?
I help homebuyers throughout the Phoenix–Scottsdale metro area and Maricopa County, including:
Scottsdale, Phoenix, Paradise Valley, Tempe, Chandler, Gilbert and Mesa, Arizona.
I can also help eligible medical professionals purchasing elsewhere in Arizona.
How Do I Find Out If I Qualify for a Physician Mortgage in Arizona?
Start by having your individual scenario reviewed.
If you're a doctor or eligible medical professional considering a home in Phoenix or Scottsdale, I'll review your:
Medical profession and degree
New or existing employment
Employment offer letter, if applicable
Estimated credit profile
Student loans
Other monthly debts
Available assets
Desired purchase price
Expected employment start date
We can then compare the physician mortgage with other financing options available to you.
You don't need to assume your student loans are too high, wait until you've accumulated months of paychecks, or automatically put 20% down before knowing your options.
Buying a Home in Phoenix or Scottsdale?
If you're a physician or medical professional planning to buy a home in Phoenix, Scottsdale or Maricopa County, Arizona, let's run the numbers before you decide how much money to put down.
Send me your profession, approximate purchase price, estimated credit score and employment start date, and I'll help you determine which available financing structures fit your situation.
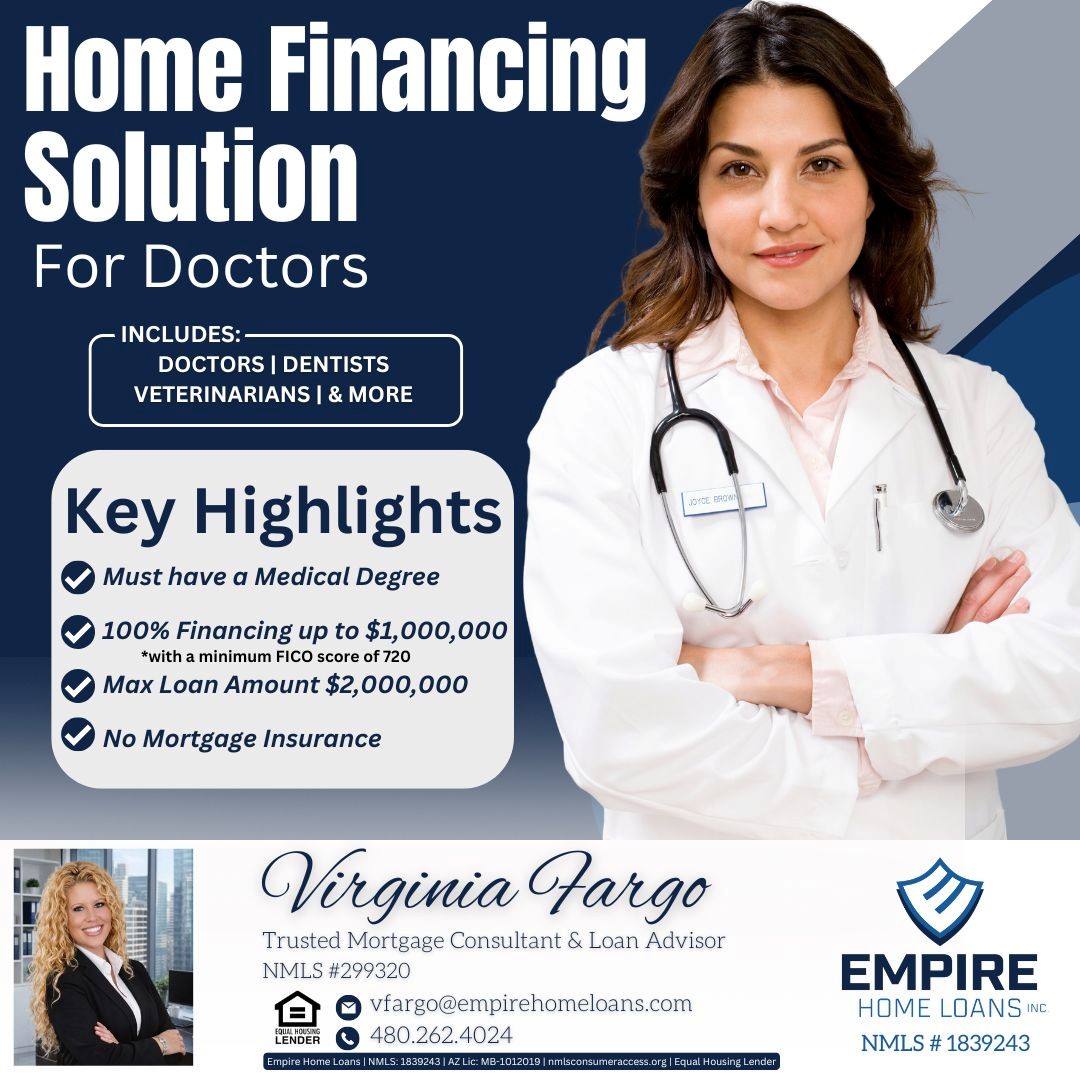
Virginia Fargo
Mortgage Loan Originator
NMLS #299320
Empire Home Loans | NMLS #1839243
AZ Lic: MB-1012019
Loan programs and guidelines are subject to change without notice. Not all borrowers or properties will qualify. 100% financing, student-loan treatment, employment offer-letter qualification, loan amounts, LTV and DTI limits are subject to applicable program requirements and underwriting approval. Closing costs and prepaid expenses may still be required.
About Virginia Fargo
Virginia Fargo, providing No Hassle Home Loans, the trusted mortgage consultant, home loan advisor in Scottsdale & across Maricopa County, the leading mortgage broker dedicated to helping consumers save money specializing in home loans, first-time homebuyers, relocation, affordability and self-employed borrower financing.